


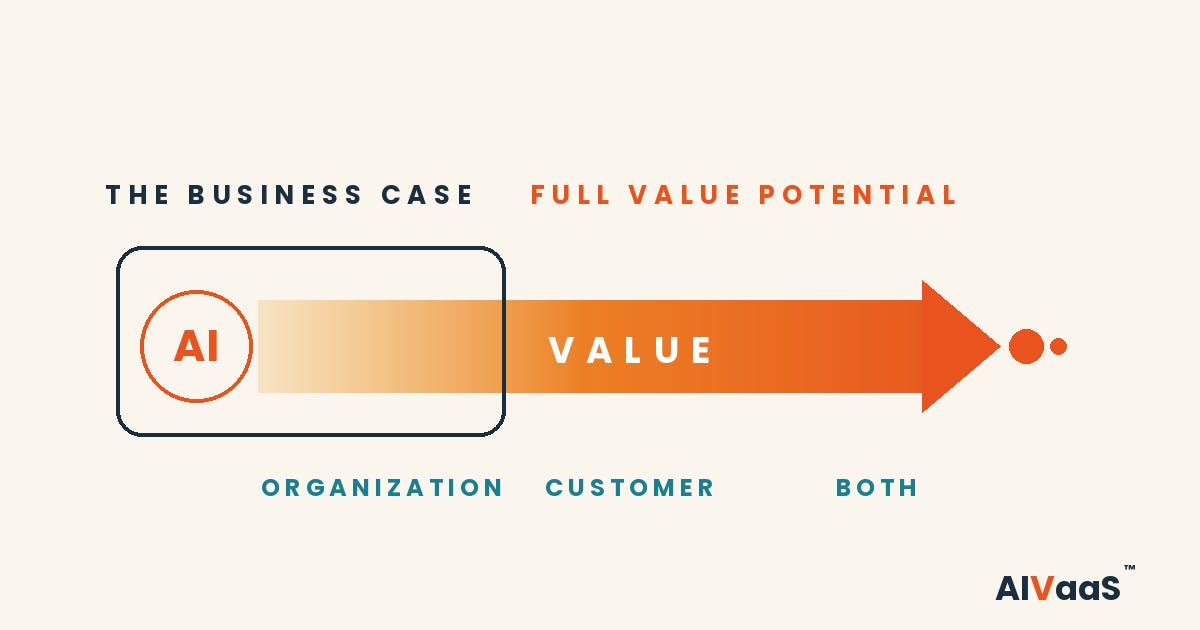
In AIVaaS™, the Value Spectrum sets out the forms value can take and who receives each one. Capital approval is where that spectrum meets the business case, and the business case reads some parts of it far more easily than others.
Two AI proposals reach the same committee on the same morning, both built on the same new capability. The first lowers the cost of a process the company already runs, and it arrives with a baseline, a comparable figure and a short payback period. The second is aimed at customers. Its value would arrive later and build gradually, and it would hold for longer once it did.
Both deserve to be considered, and both are considered. The difference is what each one can show on the day of the decision. The first is visible from a distance and starts paying back at once. The second carries a doubt about whether its value will be realised at all.
One proposal is certain and familiar. The other only looks like potential.
Every form of value reaches somebody
Value is not one thing. Every form of it names the party who has to be better off before that value can exist at all.
Cost reduction needs nobody outside the company, and it benefits the owner and the organisation. Increased profitability works the same way. Revenue growth does not, because revenue grows only when a customer has been better served, which is why the customer stands there alongside the organisation.
The AIVaaS™ Value Spectrum sets these forms out in order and names the recipient of each one. Further along it lists value-driven productivity, customer and employee experience, new revenue streams, market share and margin expansion, equity growth, and net positive impact.
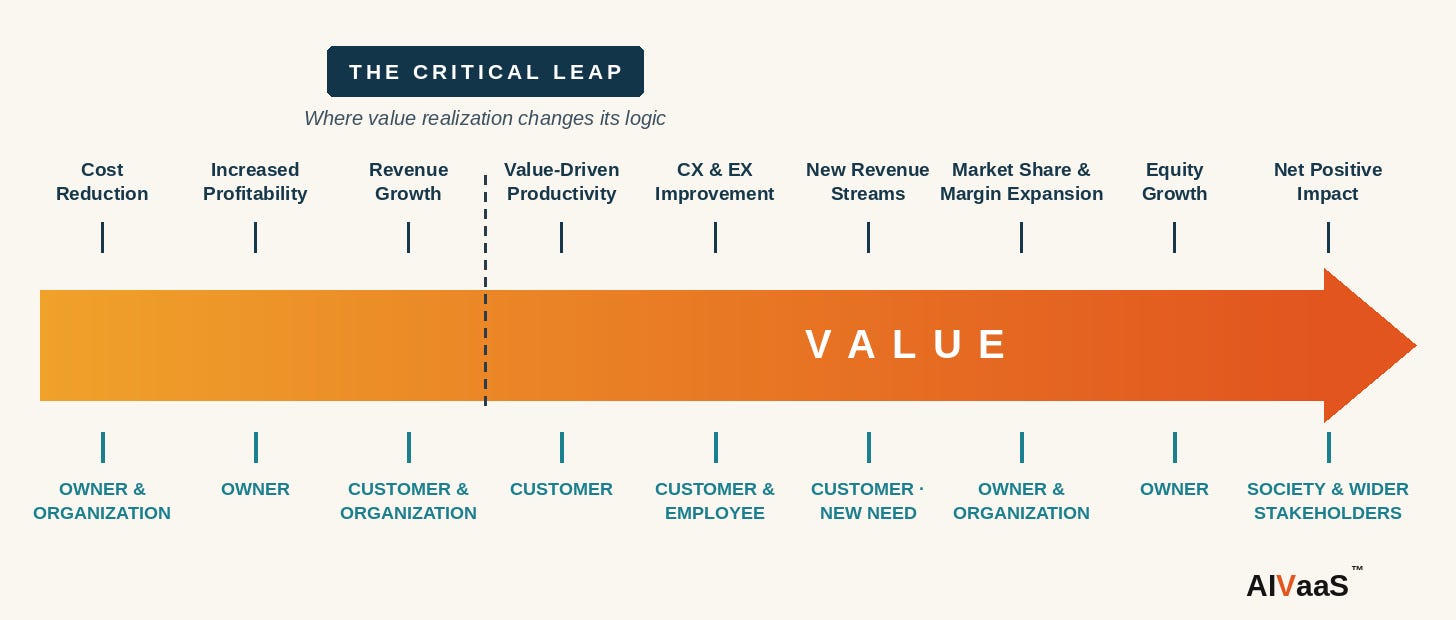
A third of the way along the spectrum sits the Critical Leap, the point where value realisation changes its logic. To the left of it, value comes from the business you already have, performing better, and it shows up on a line that already exists in your accounts.
To the right of it, value reaches the business only after it has reached somebody else. A customer has to be better served, or an employee has to work differently, before anything arrives on your side.
The same AI capability can go either way
An AI capability has no direction of its own.
Point it inward and it does the work you already do, faster and at a lower cost: fewer manual steps, shorter cycles, more cases handled in a day. Point it outward and it does something else. It finds a need nobody is covering yet, and it makes possible an offer you could not have made without it.
Earlier technology settled this question at the point of purchase. You bought a payroll system to run payroll, and nobody had to decide what it was for. AI does not arrive with a purpose attached. Somebody gives it one, and that somebody is now the person who approves the money.
One word, two kinds of productivity
A business case treats productivity as a single thing. AIVaaS™ separates it into two.
The first is productivity of execution. More work done for the same input, inside the business you already run. Shorter cycle times, more cases handled, fewer manual steps.
The second is value-driven productivity, the form that sits just to the right of the Critical Leap. It measures how many new business models you can design, test, reject and scale, and how quickly, with each one able to open a new form of value.
Both kinds run on processes. What separates them is what the productivity is aimed at, and who ends up better off.
AI contributes to the second kind differently. It reads data to show where new customer needs are forming and where existing ones are served poorly, which are patterns in what customers do with you and in what they do without you. It also shortens the path from an idea to a test, and from a test to the decision to stop.
Rejecting a business model quickly is part of this form of value rather than a failure of it. An organisation that starts many initiatives and stops none is not getting better at creating value. It is accumulating undecided commitments.
Both kinds end up in the same business case. They do not fare equally well there.
One side arrives with a calculation, the other with a claim
A business case exists to make different proposals comparable. It has done that job for decades and it does it well. Comparability needs a baseline, and cost reduction has one, because the cost already exists and the company already measures it.
The second proposal has no baseline. It rests on a judgement about whether a need outside the company will be met, and by how much. So one proposal arrives with a calculation and the other arrives with a claim, and nothing in the business case prepares it to weigh the second against the first.
This is not one company’s habit. Deloitte’s Finance Trends 2027 survey found that 36 percent of finance leaders cite time and productivity as the key metrics for evaluating AI investments, compared with 23 percent who cite revenue enablement. The report draws the conclusion itself: as AI costs rise, finance leaders will need a fuller view of value.
What fuller means is left open, and a survey is not the place to answer it. The AIVaaS™ Value Spectrum is one answer. It names the forms value can take and the party each of them has to reach, which is what a business case has to be able to state before the money moves.
The filter does not reject. It teaches
A preference built into a business case never announces itself. It works one proposal at a time, and every individual decision is defensible. The company commits to an ambition, the portfolio fills with the investments that clear the bar most easily, and a year later the portfolio shows a smaller ambition than the strategy did.
Nobody voted against the AI ambition. There was no vote.
The second effect costs more and is harder to see, because people learn what passes. After a few rounds, nobody writes the proposal that will not be approved. The narrowing happens in documents that are never drafted, and those cannot be counted, reviewed or missed.
Removing the business case does not help either. Some companies approve large AI investments on an executive mandate instead, with no measurement attached, which replaces one filter with another. The question becomes who is asking rather than what can be measured, and ambition is no safer there.
What the left side cannot defend
Cost savings are value. They protect this year’s margin and they fund everything else.
AI solutions that lower the cost of work you already do are available to almost everyone, so almost everyone will produce the same form of value from them. The saving is real, but the advantage is temporary.
A portfolio full of such savings lowers costs every year and leaves the company selling exactly what it sold before.
Cost savings hold this year’s margin. They do nothing about the reason a customer will still be a customer next year.
Where this leaves the CFO
The CFO does more than judge. Investments start in finance too, and finance often helps other functions build the case before it is ever submitted.
The decisive role is still the judging, because it is the one nobody else can do instead of them.
The reason a customer stays is decided in a place the company’s own accounts do not describe. The books record the consequence of customer value, never its cause. Reading them tells you what a customer did last year, not what would make them stay next year.
The gap between a calculation and a claim does not close on its own. Demanding the same standard of proof from both asks for something that does not exist, and dropping the standard gives up the discipline that makes the role worth having.
None of this takes the decision away from the CFO, and it should not. It does mean the ground the decision stands on has to widen. What counts as value for a customer, and which of it lasts, is knowledge the CMO works with every day and the CFO now needs.
A safeguard calibrated for one side of the spectrum will keep passing that side. Margin holds, and year after year nothing gets through that would make the company harder to replace.
That is not an error of arithmetic. It is an error of horizon.
Making both sides legible
Three changes do most of the work.
Say which form of value you are pursuing and who receives it. Every AI investment should name a form on the AIVaaS™ Value Spectrum and the party meant to benefit from it. When the recipient is not named, the investment defaults to an internal one, because internal value is the only kind that measures itself.
One distinction has to hold here. The recipient is not the Value Owner. The recipient is the party where the benefit occurs and is often outside the company, while the Value Owner is the internal role accountable for making sure it occurs and is evidenced. If those two collapse into one, the customer disappears from the investment logic, because the Value Owner is always internal.
Judge the portfolio by its composition, not by the sum of its returns. The AIVaaS™ Value Creation Matrix asks where the funded initiatives sit as a group. Several well justified investments can add up to a portfolio with less ambition than the strategy set. AI Investments Prioritization brings enabling value, dependencies and platform exposure into that view, since none of them appear in a single business case.
Decide in advance what evidence would change the decision. An investment approved on a claim needs a point at which the claim is tested, and a consequence attached to the answer: scale, redesign or stop. Value & ROI Realization carries potential, emerging and realised value into the next allocation, so that evidence improves the following decision instead of defending the last one.
Where AI ambition is settled
Strategy is where AI ambition is set. Capital approval is where it is decided.
None of this makes the second proposal win. A company can look at both sides of the spectrum and still fund the saving, for good reasons, in a given year.
What changes is that the choice is made rather than inherited. The narrowing stops being something you find in the portfolio a year later, and becomes something somebody decided, on a date, with a reason attached.
One question settles whether any of this is happening in your company. Which forms of value does our business case recognise clearly, and which intended recipients never appear in it?
What the research shows, and what AIVaaS™ adds
Deloitte’s Finance Trends 2027, published in September 2026 outlines the shift. 54 percent of finance leaders now lead enterprise AI and technology capital allocation, and the metrics applied to those investments favour productivity over revenue. It also names the limit and calls for a fuller view of value.
AIVaaS™ supplies the content of that view. Which form of value is being pursued, who is meant to receive it, who inside the company is accountable for it, and what evidence would change the next decision.